
Two different wrappers, one goal: a diversified portfolio. The right fit depends on costs, taxes, and how you like to invest.
An ETF trades on an exchange throughout the day, while a mutual fund is generally bought or sold at the next price calculated after the market closes. Both can hold a diversified mix of investments, and either can follow an index or be actively managed, so the right fit depends on costs, taxes, account options, and how you want to invest.
What’s the real difference?
The key difference is how you buy and sell shares. An ETF, or exchange-traded fund, trades through a brokerage during market hours, much like an individual stock. A mutual fund processes purchases and sales through the fund at its next calculated net asset value, or NAV.
That changes the timing and mechanics of a trade, but it doesn’t tell you what the fund invests in. An ETF and a mutual fund can both hold stocks, bonds, or other investments, and both can offer broad diversification. The fund’s holdings, fees, and investment approach matter as much as its structure.
How do ETFs and mutual funds compare?
| Feature | ETF | Mutual fund |
|---|---|---|
| Trade timing | Trades during market hours at a market price, which may differ slightly from NAV. | Orders generally receive the next calculated NAV, usually determined once each business day after the market closes. |
| Costs | Check the expense ratio, plus any applicable commission and bid-ask spread. | Check the expense ratio and whether the fund has sales charges or other fees. |
| Minimum investment | Often the price of one share; some brokers offer eligible fractional shares. | Set by the specific fund and share class; minimums vary and may be waived in some accounts. |
| Tax efficiency | Often has an advantage in taxable accounts, but distributions can still occur. | May distribute taxable capital gains in a brokerage account, even if you didn’t sell shares. |
| Automatic investing | Available through some brokers, but recurring purchases and fractional-share features vary. | Often supports straightforward recurring, fixed-dollar contributions. |
| May suit you if… | You want intraday trading, a low entry point, or a potentially tax-efficient option for a taxable account. | You value automatic fixed-dollar investing, simple end-of-day pricing, or your plan offers a suitable fund. |
These are common differences, not guarantees. Check the fund prospectus and your brokerage or retirement-plan rules before investing.
Which one costs less?
Neither structure is automatically cheaper. A low-cost index mutual fund can cost less than an actively managed ETF, and a low-cost ETF can cost less than an actively managed mutual fund. Compare the actual funds you’re considering, not just the labels.
Start with the expense ratio: the fund’s annual operating expenses as a percentage of its assets. For perspective, an expense ratio of 0.10% works out to about $10 a year on a $10,000 balance; 0.50% works out to about $50. These are simple estimates before investment returns and other costs.
Fees vary across funds, but they can add up over time. Morningstar’s 2026 U.S. Fund Fee Study reported an asset-weighted average expense ratio of 0.32% across U.S. funds in 2025, and 0.10% for passive funds. Those are broad averages, not quotes for any particular ETF or mutual fund.
ETFs can also have a bid-ask spread: the gap between the price buyers are offering and sellers are asking. A spread is a trading cost, even if you pay no commission. Mutual funds may have sales charges, sometimes called loads, or other fees depending on the fund and share class. The SEC’s guide to mutual funds and ETFs explains the main costs to review.
Why does trade timing matter?
You can place an ETF order during the trading day, and the price may move before your order fills. ETF shares trade at market prices, which can be slightly above or below the value of the fund’s underlying holdings. A limit order can help set the highest price you’re willing to pay when buying, though it may not execute.
A mutual fund order works differently. You can submit it during the day, but you generally won’t know the exact price until the fund calculates its NAV, typically after the market closes. You don’t choose an intraday price.
For long-term investors making regular contributions, intraday trading may not matter much. More frequent trading can also tempt investors to react to short-term market moves. Choose the structure that fits your plan rather than treating the ability to trade all day as an advantage you need to use.
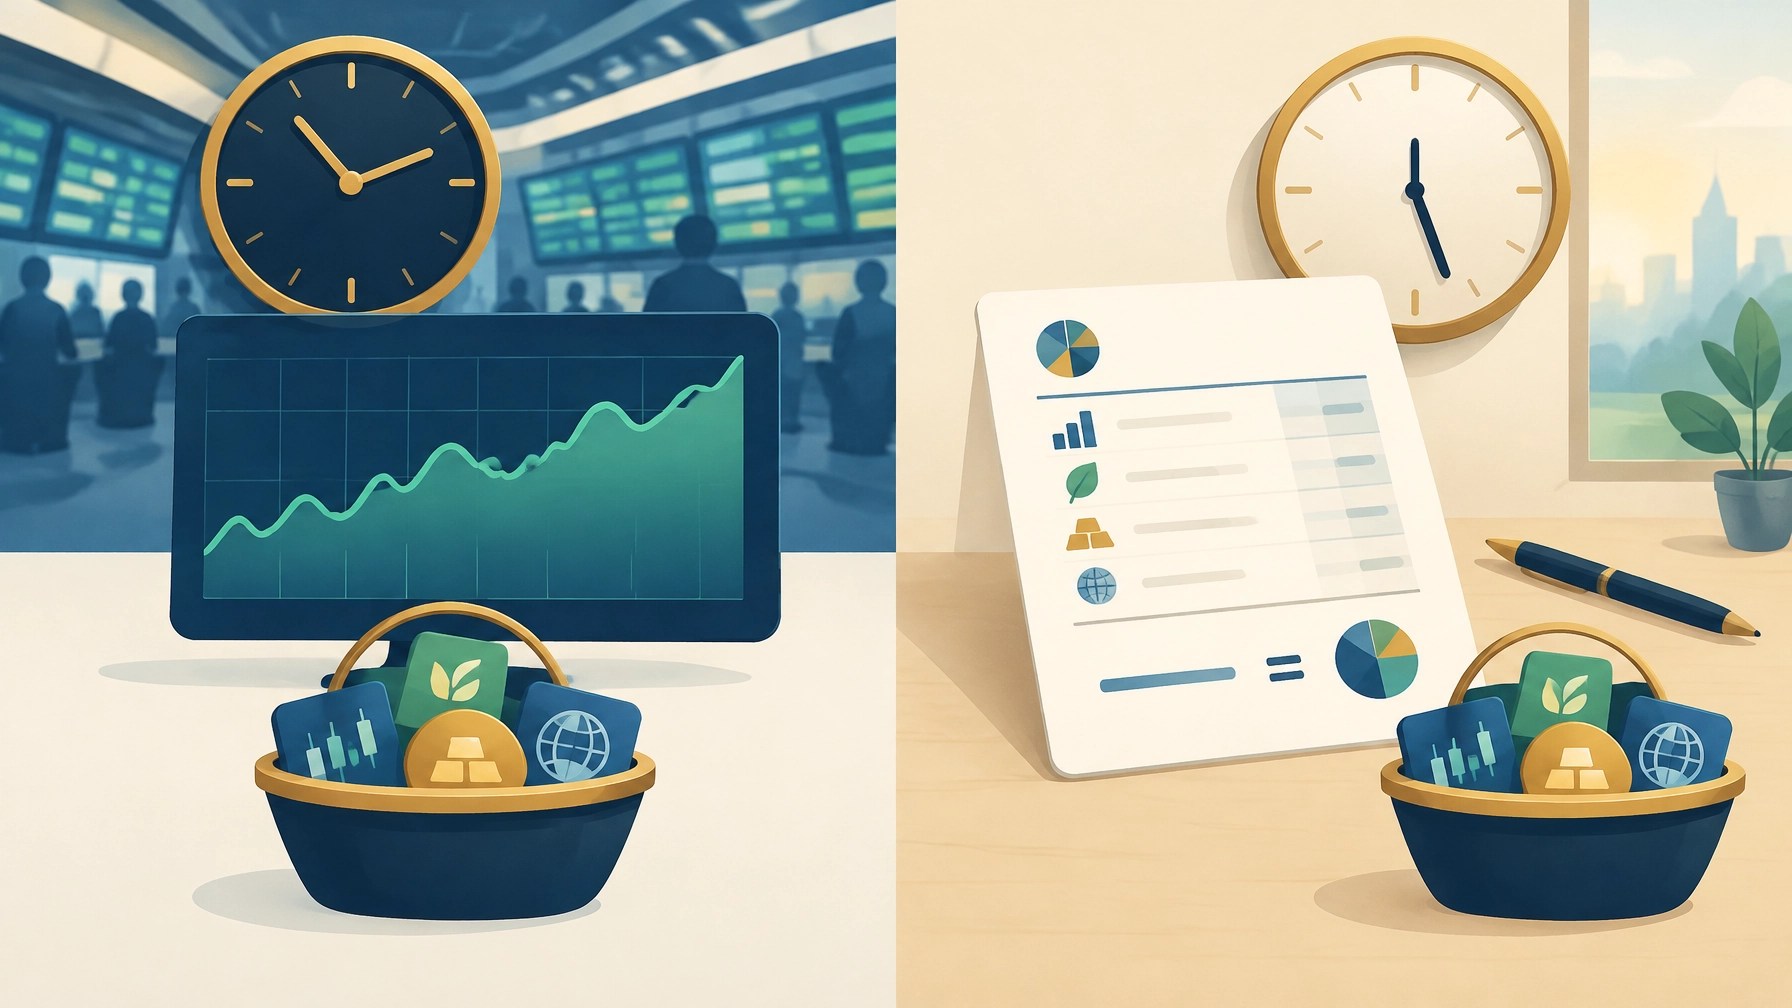
ETFs trade all day like a stock; mutual funds settle at one end-of-day price.
Is an index fund the same thing as an ETF?
No. ETF versus mutual fund describes how the fund is structured and traded. Index versus active describes how investments are selected. These are separate choices: an ETF can be index-based or active, and a mutual fund can be index-based or active.
An index fund aims to track a benchmark, such as a broad stock or bond index. An actively managed fund gives a manager more discretion to choose investments, often with the goal of outperforming a benchmark. Active management may involve higher research and trading costs, but don’t assume every active fund is expensive, or that every index fund is a bargain. Check the prospectus for the expense ratio, strategy, and benchmark.
Which one may be more tax-efficient?
In a taxable brokerage account, ETFs often have a tax-efficiency advantage. Their structure can allow some portfolio transactions to happen without the fund selling appreciated holdings and distributing the resulting capital gains to shareholders. But that doesn’t make ETFs tax-free: an ETF can still distribute taxable income or gains, and selling your own shares may create a taxable gain or loss.
Mutual funds can distribute capital gains when the fund sells investments at a profit. In a taxable account, you may owe tax on a distribution even if you didn’t sell your own shares. The IRS provides more detail on mutual fund distributions and taxes.
This difference is usually less important inside an IRA or 401(k), where investment income generally isn’t taxed the same way as it is in a taxable brokerage account. Account rules still matter, and taxes may apply to withdrawals depending on the account. If you’re unsure how distributions could affect your tax situation, consider speaking with a qualified tax professional.
Which one is better for beginners?
Either can work for a beginner. Focus first on choosing an investment approach you understand, keeping costs reasonable, and contributing consistently. A fund’s structure does not guarantee returns or tell you how much risk it takes.
A mutual fund may feel simpler if you want to invest a fixed dollar amount automatically, for example, a set contribution from each paycheck. Many funds support automatic investments, though account features and minimums differ.
An ETF may fit if the fund’s minimum investment is important to you, you want to place trades during market hours, or your broker supports recurring ETF purchases and fractional shares. Those features vary by brokerage, so check before opening an account or changing your routine.
Setting up automatic contributions: easy with many mutual funds, and possible with ETFs at some brokers.
Can you do both?
Yes. You can hold ETFs and mutual funds in the same portfolio. For example, a workplace retirement plan may offer mutual funds while a separate brokerage account offers ETFs. You might also choose funds in different structures for different goals or account features.
The important thing is to look at your overall portfolio. Two funds with different names may hold many of the same investments, which can lead to more overlap than you intended. Compare their holdings, investment objectives, fees, and role in your plan.
So, which one fits your money?
Consider a low-cost ETF if you’re investing in a taxable brokerage account, want the option to trade during the day, or need a lower starting point and your broker supports fractional shares. Keep in mind that trading prices, spreads, and tax results can vary.
Consider a low-cost mutual fund if you value automatic fixed-dollar contributions, prefer end-of-day pricing, or your workplace plan offers a suitable option. In an IRA or 401(k), compare the available funds, fees, and convenience rather than choosing based only on ETF tax efficiency.
Before deciding, compare similar funds: broad index ETF versus broad index mutual fund, for example. Review each fund’s expense ratio, minimum, investment strategy, holdings, tax characteristics, and any extra trading or account costs.
Frequently asked questions
Do ETFs and mutual funds both offer diversification?
They can. Diversification depends on what a fund holds, not whether it is an ETF or mutual fund. Check the fund’s holdings and objective to understand what you would own.
Can I invest in an ETF with a small amount of money?
Often, yes. You can usually buy at least one share, and some brokerages offer fractional shares for eligible ETFs. Availability and minimum order rules depend on the broker.
Are mutual funds safer than ETFs?
Not because of their structure alone. Risk depends on the investments inside the fund, such as stocks, bonds, or other assets. Review the fund’s holdings and strategy before investing.
Do ETFs always have lower fees?
No. Compare the expense ratios and any additional costs for the specific funds. A fund’s structure by itself doesn’t determine what it costs.
Can I automatically invest in ETFs?
Some brokerages allow recurring ETF purchases, often with fractional shares, but the feature isn’t available everywhere. Mutual funds commonly offer automatic fixed-dollar contributions; check the rules for your account.
Key takeaways
- ETFs trade during the day; mutual funds generally price transactions once daily.
- Either structure can be index-based or actively managed.
- Compare expense ratios and other costs for specific funds, not just the fund type.
- ETFs may be more tax-efficient in taxable accounts, but they can still generate taxable distributions.
- Automatic investing and minimums depend on the fund, broker, and account.
Next step: Pick the account you’re investing in, then compare two similar funds by cost, holdings, minimum, and automatic-investing options. For more financial education, visit Smart Money Spark.
This article is for educational purposes only and is not individualized financial advice.